
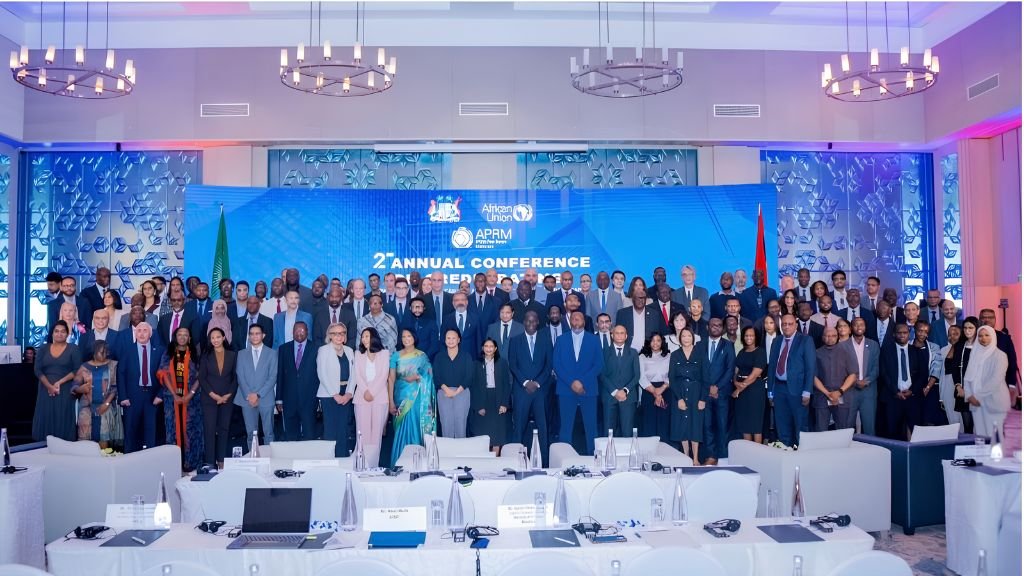
Africa’s credit rating challenge is not just about having more rating agencies. It is also about ensuring that ratings are recognised, trusted and used to inform financing decisions. This was a central theme of discussions at the 2026 Africa Rating Agencies Conference in Mauritius.
The discussions featured a roundtable convened by the United Nations Development Programme (UNDP) and AfriCatalyst on 7 October 2026, on the margins of the 2nd Africa Annual Conference on Credit Ratings and the launch of the Africa Credit Rating Agency (AfCRA). More than 50 participants from rating agencies, regulatory bodies, financial institutions, government, business associations and development organisations considered the challenges limiting the wider use of domestic credit ratings.
Building demand for domestic ratings
A key issue was the gap between the availability of rating agencies and the demand for their services. Samuel Omukoko, Managing Director of Metropol Corporation, noted that while the supply of agencies and methodologies was comparatively well structured, market demand remained underdeveloped. Participants identified greater awareness among borrowers and investors, alongside regulatory recognition, as important to encouraging wider use of ratings.
Participants also highlighted that limited recognition by regulators and public institutions can prevent ratings from informing lending, investment and public procurement decisions. Strengthening credibility, transparency and regulatory supervision was therefore considered essential to building confidence in domestic rating markets.
Improving cross-border integration and comparability
Fragmented regulatory frameworks, licensing requirements and limited portability of credit information were identified as obstacles to assessing businesses across African markets. Mavis Owusu-Gyamfi, President and CEO of the African Center for Economic Transformation (ACET), emphasised the need to let finance follow businesses across borders, especially as regional value chains expand.
Discussions highlighted several measures that could strengthen domestic rating markets and support wider use of credit assessments:
- Regulatory coordination: Improve cooperation among regulators and explore regional licensing arrangements to reduce barriers across markets.
- Comparable credit assessments: Develop common reference points that help investors interpret credit risk consistently across jurisdictions.
- Broader data access: Incorporate reliable alternative data, including transaction flows, utility and rental payments, supply-chain records and operational information, particularly when assessing SMEs with limited formal credit histories.
- Technology-enabled assessment: Use digital tools and artificial intelligence to reduce assessment costs and improve monitoring, while retaining professional judgement and appropriate oversight.
- Stronger market capacity: Improve analytical expertise and awareness of credit ratings among businesses, investors and other market participants.
These measures reflect the need for greater consistency and cooperation without necessarily requiring African rating agencies to adopt identical methodologies.
Data comparability and the users of risk information
Oladele Adeoye, Chief Rating Officer of DataPro Limited, highlighted the different users of risk information, including investors and lenders, regulators, company management, counterparties and suppliers, and policymakers. Their decisions depend on information that is relevant, timely, verifiable, and comparable.
Adeoye proposed an African probability-of-default standard as a common reference point for comparing credit risk across markets. The proposal would support greater comparability while allowing rating agencies to retain their individual methodologies and identities. This distinction is important because comparability does not necessarily require uniformity in rating approaches.
Strengthening the institutional framework
Beyond data and technology, participants stressed the importance of building analytical capacity, improving awareness of credit ratings and strengthening cooperation among regulators. The discussions also considered practical ways to stimulate demand, including closer engagement with investors and transaction advisers and testing lower-cost digital credit-scoring tools for mid-sized businesses.
In his closing synthesis, Daouda Sembene, President and CEO of AfriCatalyst, highlighted the potential of stronger domestic rating ecosystems to deepen local-currency capital markets, mobilise domestic investment, reduce financing costs and improve access to longer-term funding.

Leave A Comment